
[RAM] RAM Ratings affirms Zamarad's Tranche 3, 5, 8, 9, 10 and 11 Sukuk ratings
RAM Ratings has affirmed the ratings of all rated classes under Zamarad Assets Berhad’s Tranche 3, 5, 8, 9, 10 and 11 Sukuk Murabahah, and revised the outlook on Tranche 8 Class B Sukuk to positive from stable (see table). Zamarad is a special-purpose vehicle incorporated to undertake the securitisation of personal financing (PF) facilities extended to civil servants, originated through the business partners of RCE Marketing Sdn Bhd (RCEM).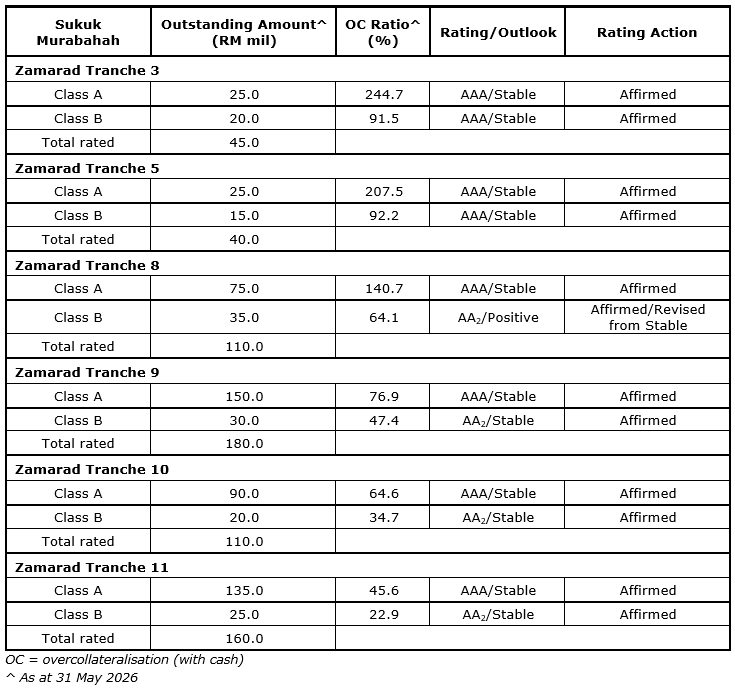
The rating affirmations are anchored by the underlying receivables’ satisfactory performance, with default and prepayment trends remaining broadly consistent with our expectations. Based on our review of RCEM’s static pools originated between April 2021 and May 2026, asset performance has remained stable relative to our previous assessment, supporting the retention of our base case assumptions. Available credit enhancement for the tranches under review continues to provide adequate protection commensurate with their respective ratings. The positive outlook on Tranche 8 Class B Sukuk reflects our expectation that the accumulation of additional credit enhancement will support an upgrade over the next 12 to 15 months.
Tranche 3 and 5 Sukuk are already fully cash-backed, hence repayment of obligations under the Sukuk are no longer dependent on future performance of the securitised receivables portfolio. For Tranches 8, 9, 10 and 11 which feature a Revolving Option, we expect the utilisation of excess cash reserves for the purchase of new receivables, if any, to at least preserve required credit support for the respective AAA and AA2 ratings of the Class A and Class B Sukuk, in line with the transaction terms.
Over the review period, default performances across all portfolios were largely within expectations, despite some fluctuations attributable to collection timing and administrative delays. Considering the non-discretionary salary deductions through which the PF facilities are repaid and the low civil service attrition rate, default and delinquency levels are expected to remain stable. Average prepayment rates since issuance for the portfolios remained within our high and low scenarios. As prepayments are typically event-driven and tend to rise as the underlying PF receivables season, we anticipate a gradual increase in prepayment, driven by continued refinancing activity amid cost-of-living pressures, albeit within the range of our assumptions.
Analytical contacts
Tan Yan Choong
(603) 2708 8256
yanchoong@ram.com.my
Lim Chern Yit
(603) 2708 8302
chernyit@ram.com.my
Media contact
Sakinah Arifin
(603) 2708 8212
sakinah@ram.com.my