
[RAM] RAM Ratings affirms Genting Group's AA1 ratings with negative outlook; timely execution remains key
RAM Ratings has affirmed the AA1/P1 corporate credit ratings of Genting Berhad (Genting or the Group) and Genting Malaysia Berhad (GenM), as well as the issue ratings of their respective debt programmes (Table 1). GenM’s ratings reflect its close operational integration with Genting and our expectation of a ‘very high’ likelihood of parental support, if needed. We have maintained the Negative outlook on the long-term ratings, reflecting the Group’s rising debt and weak operating performance.
The affirmation reflects Genting’s strong business profile, underpinned by leading market positions in Malaysia, Singapore and New York State; we expect material uplift in forward earnings as sizeable expansion projects in these markets are completed. The ratings also considered the issuance of USD1.25 bil subordinated perpetual securities in April 2026 and a proposed RM1.25 bil rights issue expected to be completed by 1Q 2027. Both measures will partly ease balance sheet pressure but will not entirely restore key financial metrics to within our rating thresholds before FY Dec 2028. This is because with capex and investment requirements doubling up to RM10 bil annually on average, we forecast net debt to rise to about RM35 bil by end-2028 from RM22.94 bil as at end-2025, temporarily straining the balance sheet and increasing the Group’s reliance on capital market and bank funding.
We expect earnings recovery to be driven by a considerable ramp-up in business volumes at Resorts World New York City (RWNYC) and Resorts World Sentosa (RWS), and earnings accretion from commencement of operations at several oil and gas blocks. We also expect earnings to lift from lower gaming tax rates on slots at RWNYC and increasing economies of scale. Despite the higher debt, earnings growth should improve the net debt to operating profit before depreciation, interest and tax (OPBDIT) ratio to about 3.0 times, while funds from operations (FFO) net debt coverage is projected to recover to above 0.3 times by end-2028. Net gearing is expected to rise towards 0.60 times by end-2028, despite the perpetual securities issuance and planned rights issue. All said, Genting’s recovery hinges on execution of its business and expansion plans according to timeline and within budget.
We may revise the outlook to stable if execution remains broadly on track and operating performance that leads to key financial metrics meeting rating thresholds. The Group remains supported by RM17.64 bil of unencumbered cash as at end-June 2026. Its strong liquidity, financial flexibility and track record of refinancing through bank and debt capital markets provide an important buffer against limited headroom for material execution delays or operating shortfalls. Conversely, any of these triggers falling materially short of our projections would increase downward rating pressure.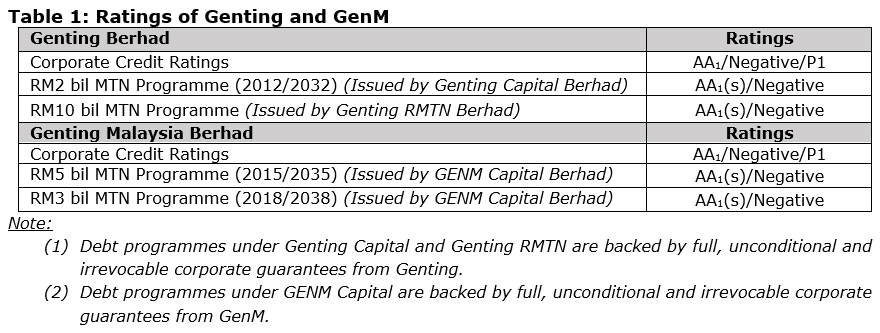
Analytical contacts
Ben Inn
(603) 2708 8290
ben@ram.com.my
Thong Mun Wai
(603) 2708 8255
munwai@ram.com.my
Media contact
Sakinah Arifin
(603) 2708 8212
sakinah@ram.com.my