
[RAM] RAM Ratings revises ORIX Leasing and ORIX Credit's AA2 ratings to positive
RAM Ratings has revised the outlook on the long-term AA2 issue ratings of ORIX Leasing Malaysia Berhad’s (OLM or the Company) and ORIX Credit Malaysia Sdn. Bhd.’s (OCM) debt programmes to positive from stable. Concurrently, we have affirmed the Company’s short-term P1 issue rating.
The outlook revision reflects our more favourable assessment of the credit strength of ORIX Corporation (ORIX Corp or the Group), the Company's ultimate parent which is a diversified multinational financial services group established in Japan, and the resulting enhancement in support considerations. Our positive view of ORIX Corp is driven by its strengthened financial profile, underpinned by resilient earnings, a diversified business portfolio, sound risk management and disciplined execution of its capital recycling strategy, while maintaining robust liquidity and comfortable gearing.
The Group’s profit before tax jumped 44% y-o-y to JPY691.4 bil in FY Mar 2026 translating into a return of asset of 4.0% (FY Mar 2023 – FY Mar 2025 average: 2.8%). Even excluding a large disposal and valuation gain from an energy-related investee, pre-tax profit would have increased by more than 20%, reflecting strong underlying earnings generation. Despite its significant financial services operations, gearing improved to a comfortable 1.3 times as at end-March 2026 (end-March 2023: 1.6 times). Liquidity also remained strong, with diversified funding sources and established access to capital markets and bank funding providing a healthy 2.8 times cover over short-term debt as at end-June 2026 (excluding life insurance operations; end-March 2025: 3.1 times).
OLM’s and OCM’s ratings incorporate an uplift based on RAM’s assessment of a ‘high likelihood’ of extraordinary support from ORIX Corp, underpinned by its strategic importance to the Group. Parental support is demonstrated through guarantees on nearly all the Company’s bank borrowings, provision of funding lines and close operational oversight. OCM, a wholly owned subsidiary of OLM, contributed over half of the Company’s pre-tax profits in FY Mar 2026 and is highly integrated with the Company. As such, the credit profiles of the two entities are closely aligned.
On a standalone basis, OLM’s established domestic position in the hire-purchase and leasing market continues to be a key strength underscoring its credit profile. OLM’s pretax profits of RM117.7 mil in FY Mar 2026 was broadly unchanged from the preceding year. Receivable growth was moderate at 2% (FY Mar 2025: 10%) given the more cautious approach adopted by both the Company and its SME borrowers amid the heightened macroeconomic and geopolitical uncertainties.
Asset quality remained robust, with OLM’s gross impaired financing ratio holding steady at a commendable 1.2% as at end-March 2026. The Company has limited direct exposure to the Middle East and US tariff-related risks and has not observed any material asset quality deterioration to date. We expect any near-term asset quality pressures to be contained, although the full impact of a softer macroeconomic environment on borrowers may take time to emerge.
OLM continues to exhibit balance-sheet strength. Gearing rose to 2.6 times as at end-March 2026 (end-March 2025: 2.1 times) primarily due to a higher dividend payout, but the metric remains healthy. Liquidity position was also strong, with cash reserves and unutilised facilities providing 3.3 times coverage of short-term obligations.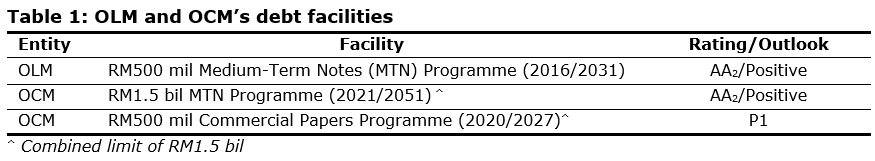
Analytical contacts
Chew Chiang Lim
(603) 2708 8297
chianglim@ram.com.my
Wong Yin Ching, CFA
(603) 2708 8280
yinching@ram.com.my
Media contact
Sakinah Arifin
(603) 2708 8212
sakinah@ram.com.my