
[RAM] RAM Ratings upgrades Sunway REIT's CCR to AA1/Stable; related debt issue ratings also upgraded
RAM Ratings has upgraded the corporate credit ratings (CCRs) of Sunway Real Estate Investment Trust (Sunway REIT or the REIT) to AA1 from AA2, with a stable outlook and affirmed its short-term CCR at P1. The ratings of debt facilities issued under its funding vehicles have also been upgraded or affirmed, as applicable (see table). The suffix (s) indicates rating enhancement from inter-company payments by the REIT.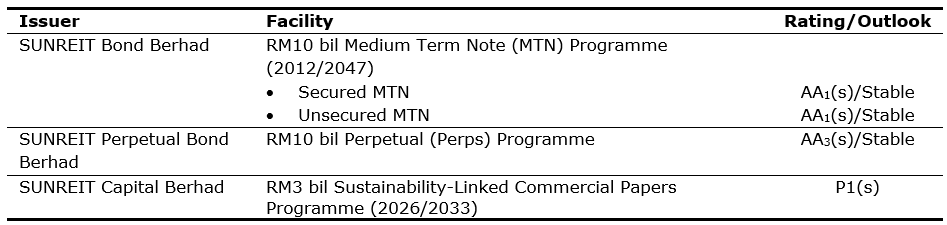
The rating upgrade reflects RAM’s assessment of a ‘high likelihood’ of extraordinary support from Sunway Berhad, if needed, and our view of Sunway Berhad’s now stronger credit profile. We consider the REIT’s strategic role in the Group’s build-own-operate and capital recycling model, common branding, Sunway Berhad’s significant ownership of both the REIT and its manager, and the REIT’s material contribution to the Group’s assets and recurring earnings. Sunway REIT’s CCR therefore benefits from a one-notch uplift from its standalone credit strength.
The ratings also recognise Sunway REIT’s continued strength as a market leader as Malaysia’s second largest M-REIT, with 28 assets across the retail, hospitality, office and industrial segments. Its business profile is anchored by prime assets, especially in the mature and integrated Sunway City development, a broad base of about 1,700 tenancies and resilient retail earnings. Retail income nonetheless, remains a core contributor of portfolio NPI. This stood at 81% in 1H fiscal 2026, with revenue and NPI rising 10.3% and 15.5% y-o-y, respectively. The REIT also recorded positive rental reversions and tenancy renewal rates of more than 90% across multi-tenanted retail assets.
Sunway REIT’s financial profile remains broadly stable, supported by resilient earnings, healthy margins and adequate funding access. Revenue rose 16.6% y-o-y to RM894.33 mil in FY Dec 2025, while NPI margin stayed robust at 74.0%. As at end-June 2026, leverage was moderate at 0.42 times, although debt-to-OPBDIT remained elevated at 7.54 times relative to similarly rated peers. Fixed charge cover of 3.42 times provides adequate headroom at the current rating level. We view refinancing risk to be manageable as shown in its moderate annual rollover rate of 47.0%, supported by Sunway REIT’s demonstrated access to bank and capital-market funding, available committed undrawn facilities of RM9.8 bil, diversified funding sources and efforts in spreading out its debt maturities.
The unsecured MTNs and SLCP Programme are aligned to the REIT’s long-term CCR, given their senior unsecured ranking while the Perps are rated two notches below the CCR to reflect higher loss absorption characteristics arising from discretionary coupon deferral, deep subordination and limited priority above common equity.
Analytical contacts
Tan Han Nee
(603) 2708 8322
hannee@ram.com.my
Tan Yan Choong
(603) 2708 8256
yanchoong@ram.com.my
Media contact
Sakinah Arifin
(603) 2708 8212
sakinah@ram.com.my